

Travel insurance with motorcycle, scooter and moped cover
Expert tips for choosing great motorcycle travel insurance cover for you
Our Chief Executive – General Insurance, Adrian Taylor, has a few tips for helping you choose a great travel insurance policy with scooter, motorbike and moped cover.
Adrian Taylor
Chief Executive – General Insurance
Check the automatic inclusions on your policy
You’ll commonly need to purchase extra cover to be covered while riding; however, some policies may offer this cover automatically, so always check the inclusions of your travel insurance policy before purchasing.
Know the engine capacity of your rental vehicle
Some policies will only cover the engine size for your motorcycle or moped up to a certain amount (e.g. 250cc), so if you’ve already booked a motorbike with a rental company, make sure the engine capacity is covered by your policy.
Consider what other cover you need
While it’s important to be covered for riding a motorbike or scooter, you should also weigh up comprehensive travel insurance cover, which may financially protect you, your belongings and your trip against unforeseen events such as medical expenses, cancellations, theft and more.
The basics of getting travel cover for 2-wheeled vehicles
Getting travel insurance with scooter cover or for a motorbike or moped starts with choosing a policy that offers cover for that vehicle, checking you meet the eligibility requirements for that policy (e.g. holding a valid licence, only riding vehicles with a particular engine capacity, meeting age requirements) and understanding any exclusions before you travel overseas.
Why would I need motorbike cover in travel insurance?
A motorbike cover add-on to overseas travel insurance can provide cover when you’re riding a motorbike or any other 2-wheeled vehicle overseas. If you’re involved in a motorcycle accident while travelling, this type of insurance may help cover the resulting medical costs. Depending on the policy, you may be covered for overseas medical expenses arising from a motorbike accident, emergency repatriation or medical evacuation costs, trip cancellation due to an accident and personal accident benefits, though sub-limits may apply.
How can I get travel insurance cover for riding motorcycles?
To get overseas travel insurance cover for motorbikes, you may need to hold the appropriate domestic licence and you should only ride a vehicle that matches the cover you select. It’s important to ensure that you meet any eligibility criteria from the insurer before you apply for cover. Once you have chosen your travel insurance policy and relevant motorbike riding add-on, you will be covered for the vehicle you are planning on riding overseas. It is crucial to review the Product Disclosure Statement before you purchase a policy to check what’s covered, and what is excluded from cover, especially if you plan on riding a motorcycle on your travels. You should also consider reading the Target Market Determination to check your suitability for a policy.
Is motorcycle, scooter and moped cover automatically included in my travel policy?
Not always as travel insurance policies will often exclude motorcycles, scooters and mopeds from their standard policies. However, you may be able to purchase motorcycle cover for an additional premium.
What’s included in motorcycle, scooter and moped travel cover?
Motorbike, scooter or moped travel insurance typically includes emergency medical costs or hospital costs if you are injured in an accident involving that vehicle overseas. Depending on your level of cover, you can also be covered for emergency evacuation and repatriation back to Australia; just make sure you understand the exclusions on your policy relating to wearing helmets and obeying road rules. You may also receive 24-hour emergency assistance through your insurer via phone, email or a chatroom. Without motorcycle cover, you will typically need to cover these costs yourself, which could put you back thousands of dollars.
What are travel insurance exclusions for motorcycle riding?
Common exclusions in travel insurance claims related to motorbike riding include being unlicensed or breaking the law. Policy exclusions differ between insurers, but some common travel insurance exclusions relating to 2-wheeled vehicles include:
- riding a motorcycle, moped or scooter that’s more powerful than what’s covered by your policy
- racing, speeding, disobeying a country’s road laws or driving recklessly
- being intoxicated by an illegal substance or alcohol
- not wearing a helmet
- driving without a motorcycle licence that’s valid in your destination country
- driving in a professional capacity, such as participating in a competitive or professional event.
Furthermore, your travel insurance policy may cover personal liability in some situations, however this cover is not extended to liability that may arise if you’re riding a motorcycle or driving other vehicles. This means that you will not be covered if you damage another vehicle or injure a person while riding or driving.
Check the Product Disclosure Statement to know exactly what’s included and what’s excluded. Knowing to what extent an insurer covers these instances can help provide peace of mind when motorcycle touring or exploring an international destination from the seat of a motorbike.
Who can get travel insurance with motorcycle cover?
Anyone who plans to ride a motorbike overseas and meets the insurer’s eligibility requirements can get travel insurance with motorcycle insurance. Before purchasing the policy with motorcycle cover, it’s important to understand who is eligible for coverage, including whether you’re covered as a passenger, whether you’re covered if you have pre-existing medical conditions, or whether coverage exists as a learner bike rider.
Am I covered by travel insurance if I’m a passenger on a motorbike?
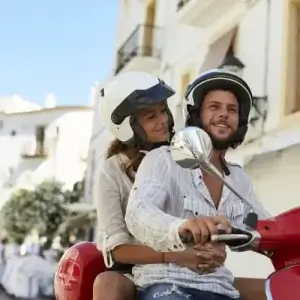
Yes, travel insurance with a motorbike add-on could cover you as the passenger on a motorcycle, provided you meet the eligibility requirements of your insurer – which may include things such as complying with local road rules and laws or riding with a helmet. You could be covered as a passenger so long as the driver:
- has appropriate insurance (that states pillion passengers are covered)
- has a licence to ride motorcycles in that country
- is in control of a motorcycle, moped or scooter with an engine that falls within the insurance policy’s bounds.
Having this cover in your travel insurance can be handy for couples who plan on travelling together on one hired bike. However, coverage for passengers may vary among insurers, so you should always thoroughly check your policy details to see how much a policy provides for a passenger on a motorbike.
Most policies will require you to wear a helmet, whether you are in control of the bike or riding as a passenger.
Can learner riders be covered for riding a motorcycle overseas?
No, learner riders are typically not covered for riding a motorbike overseas under a travel insurance policy, as the policy will likely require you to hold the relevant provisional or higher domestic motorbike licence. Requirements will vary between insurers, so make sure to check the details of your policy before you plan to ride a motorbike overseas so you can be covered.
Can I still be covered for motorbikes if I have a pre-existing medical condition?
Yes, you can still get motorbike or scooter cover if you have a pre-existing condition, but you’ll typically need to declare it with your insurer first. Not all conditions are covered, however, and depending on the nature of your condition, you may have to pay an additional premium for it to be covered. It’s possible that cover may be automatically included, covered for an additional premium, or excluded entirely. It’s worth comparing different travel insurance providers so you can be confident that you are covered if you have a pre-existing medical condition.
Check out our full guide on pre-existing medical conditions here.
Can I still get annual cover with motorcycle and scooter protection?
Yes, you can still be covered for a motorbike on an annual multi-trip policy. Once included in your travel insurance policy, it can help provide the eligible cover you’re after for motorbike or scooter-related incidents on covered trips, subject to your policy’s terms and conditions.
What do I need to know when riding a motorbike overseas?
When driving a motorbike overseas, you will need to know if you need an International Driving Permit alongside your licence, what factors could lead to your insurance claim getting rejected and the licence requirements for your travel destination.
What is an IDP?
An IDP, or International Driving Permit, is an official document that is a translation of your Australian licence into multiple languages. It allows authorities overseas to verify your credentials to operate a vehicle. Essentially, it looks like a little A6 book that contains multiple translations of your licence. It must be purchased in Australia before you depart internationally. It is typically valid for 12-month periods and is not a substitute for your licence, just an official translation of it.
Depending on which country you’re heading to, you might need an International Driving Permit, as some countries may not accept an Australian licence on its own. China, Brazil, Uruguay, Ethiopia and several other countries do not recognise it as an official document.
What do I need to be aware of when riding a motorbike overseas?
 When riding overseas, it’s important to understand road conditions, licensing requirements and what happens if you damage a vehicle. In many Southeast Asian countries such as Thailand, Laos and Cambodia, road safety is not as high a priority as in Australia. Motorcyclists and car drivers alike often speed, ignore road rules and grapple for space on the road. Accidents are common, so driving with care and caution is extremely important for your safety.
When visiting places such as Bali, Indonesia, tourists often drive scooters and motorbikes without a valid licence. Not only can this get you into legal trouble, but also, without a valid driver’s licence, you cannot claim on any injuries if you have an accident on your 2-wheeled vehicle. Penalties for disobeying local driving laws can range from fines to jail time or even deportation.
Unlike with renting a car, when renting a motorcycle, scooter or moped, your travel insurance policy won’t cover the rental vehicle excess if you have an accident. This means any damages to your vehicle are paid directly out of pocket. Your motorcycle cover may cover medical treatment or hospital expenses if you’re injured while riding, as long as no exclusions apply to your loss.
What are some common reasons motorcycle travel insurance claims get rejected?
Common reasons for a motorbike insurance claim being rejected include riding without a correct licence, not purchasing motorcycle cover and not riding with a helmet or safety gear. Keep in mind before you get on the bike:
- Licence: Policies will require you to hold a valid Australian motorbike licence, as claims arising for unlicensed driving are often rejected.
- Being uncovered by insurance: Standard travel insurance policies will frequently exclude motorbike riding, unless you specifically add it. It may be labelled ‘motorbike cover’ but could also be under an ‘adventure insurance’ add-on.
- Safety first: Coverage will typically depend on you following local laws – including helmet requirements.
- Drugs or alcohol: Claims where any kind of intoxication was involved are often excluded.
- Professional rider: Travel insurance policies will exclude any sort of ‘professional’ event – where you are riding in a competition, racing, motocross, or off-road riding.
- Dangerous riding: Claims will likely be denied if you are riding unlawfully or breaking safety rules.
Meet our travel insurance expert, Adrian Taylor
As a General Insurance expert with over 13 years’ experience in financial services, Adrian Taylor believes in educating customers about the importance of travel insurance so that anyone can kick back and make the most of their time away from home. While no one wants a disrupted holiday, a suitable travel insurance policy can provide a financial safety net for yourself, your belongings and your trip in case things go wrong.